The Velocity of Money: How It Shapes the Economy
September 11, 2026
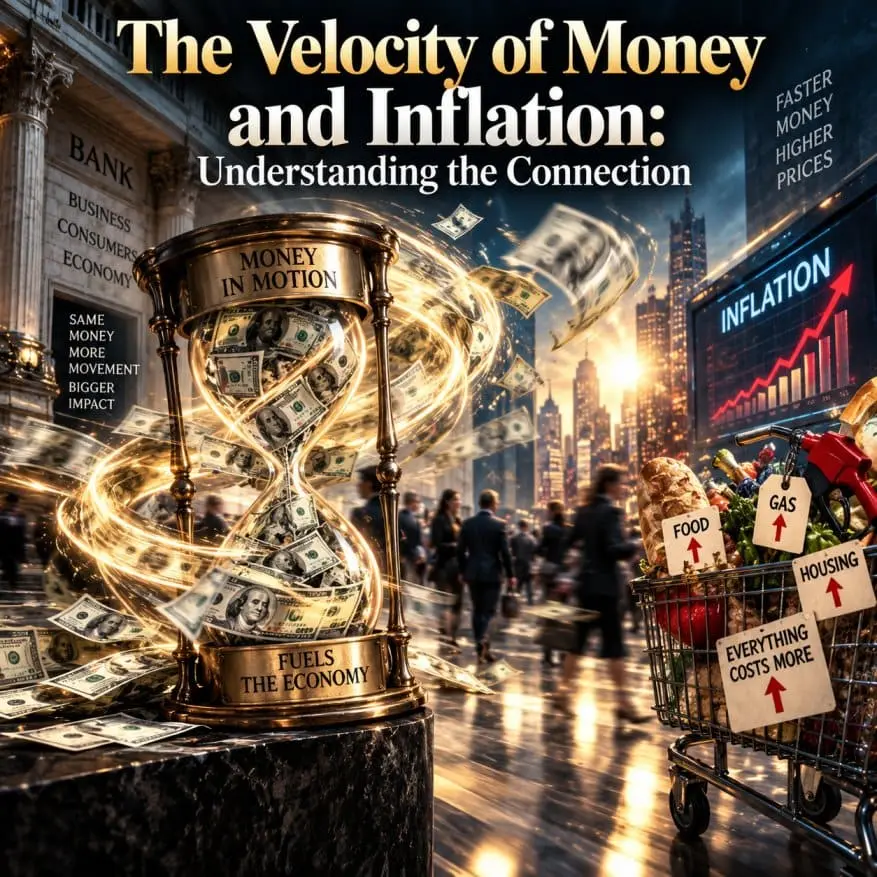
The velocity of money is one of those economic concepts that looks deceptively simple until you realize how much information is hidden inside it. Money can be created, accumulated, borrowed, saved, invested, or spent, and those actions do not have the same economic consequences because the same dollar can sit dormant for months or circulate repeatedly through the economy. That is why velocity matters: it helps reveal whether the money already present in the financial system is actually moving through economic activity or remaining relatively inert.
The deeper lesson is psychological as much as monetary. An economy can be flooded with liquidity without generating proportionate inflation if households and businesses prefer to save, banks restrict lending, or investors simply recycle capital through financial assets, while a smaller monetary expansion can become considerably more inflationary when confidence, credit creation, spending, and turnover accelerate simultaneously. The machine does not respond merely to how much money exists; it responds to how quickly that money moves.
Velocity Is the Transmission Mechanism
The standard identity is straightforward:
M × V = P × Y
Money supply multiplied by velocity equals the nominal value of economic output, represented by the price level multiplied by real output. The equation does not prove that higher velocity automatically produces higher consumer inflation, because nominal GDP can increase through a combination of higher prices and higher real production, but it does reveal something extremely important about the transmission mechanism.
If money supply rises while velocity collapses, the increase in money may have a much smaller immediate effect on nominal spending than headline monetary growth would suggest. If money supply rises while velocity simultaneously accelerates, however, the potential impact on nominal demand becomes much more powerful.
That distinction explains why the post-2008 period confused so many forecasters. The Federal Reserve dramatically expanded its balance sheet, yet money velocity fell sharply, credit transmission remained impaired, and inflation stayed comparatively subdued for years. The money existed, but much of the system was not moving it with sufficient speed to create the kind of broad demand pressure many commentators expected.
The Post-COVID Shock Changed the Equation
The pandemic created a fundamentally different monetary environment because policy moved beyond simply supporting the banking system and included enormous fiscal transfers, direct household support, emergency lending, and other measures designed to keep spending alive while large sections of the economy were effectively shut down.
At the same time, households accumulated substantial savings and then began spending as restrictions disappeared, supply chains struggled to keep up, and demand shifted rapidly toward goods and later services. The result was not simply “money printing equals inflation,” because several forces were interacting simultaneously, but the combination of monetary expansion, fiscal transfers, supply constraints, reopening demand, and changing spending behaviour created a much stronger nominal-demand impulse than the post-2008 economy had experienced.
This is the distinction the original narrative often misses. Money supply creates potential purchasing power; velocity determines how aggressively that purchasing power is transmitted through the economy.
Velocity Is Moving Again
The latest data make this particularly interesting. According to the Federal Reserve Bank of St. Louis, M2 velocity reached 1.415 in the second quarter of 2026, up from 1.395 in the second quarter of 2025 and 1.409 in the fourth quarter of 2025. That is not a dramatic resurgence, and velocity remains far below the levels seen before the financial crisis, but the direction has changed from the prolonged downward trend that dominated much of the post-2008 era.
Meanwhile, M2 itself reached approximately $23.22 trillion in July 2026, continuing its post-pandemic recovery after the sharp contraction that followed the 2022 monetary tightening cycle. This combination deserves attention because rising money supply and rising velocity together create a very different environment from rising money supply accompanied by collapsing velocity. The current movement is not evidence that hyperinflation is inevitable, but it does suggest that the monetary transmission mechanism is no longer as dormant as it was during the decade following the financial crisis.
Inflation Is More Than Velocity
This is where precision matters. Velocity does not cause inflation by itself, just as money supply does not automatically produce inflation every time it increases, because inflation ultimately reflects the interaction between monetary conditions, aggregate demand, productive capacity, wages, commodities, expectations, fiscal policy, and supply constraints.
The latest inflation data illustrate the point. U.S. headline PCE inflation was running at 3.7% year over year in July 2026, while core PCE was 3.3%, both materially above the Federal Reserve’s 2% longer-run objective.
At the same time, the current inflation problem is being complicated by forces that have little to do with domestic money velocity alone. Oil has moved above $100 per barrel amid geopolitical disruption, Treasury yields have risen sharply, and markets are increasingly concerned that energy costs could keep inflation elevated even as economic growth slows. Reuters reported on September 11 that the U.S. 10-year Treasury yield was approaching 5% while markets were assigning a substantial probability to another Federal Reserve rate increase. The result is a more complicated inflationary environment than a simple monetary equation can capture.
The Great Velocity Experiment
The post-2008 period was effectively a giant experiment in what happens when money creation increases while circulation remains weak. Banks received enormous amounts of liquidity, but the transmission into broad consumer demand was comparatively limited, and investors frequently preferred financial assets, cash, or reserves over aggressive consumption.
The pandemic produced the opposite experiment. Governments and central banks simultaneously attacked the economic contraction with extraordinary monetary and fiscal measures, households received direct support, savings accumulated, and reopening unleashed pent-up demand into an economy whose supply capacity had been damaged by lockdowns and logistical disruptions.
The difference was not simply the quantity of money. It was where the money went, how quickly it moved, and what the economy was capable of producing when it arrived. That is why velocity deserves to be watched alongside money supply rather than treated as an isolated inflation indicator.
The M1 and M2 Trap
The original article places considerable emphasis on the relationship between M1 and M2, but this needs to be handled carefully because the Federal Reserve changed the construction of M1 in May 2020, incorporating savings deposits into the aggregate. That structural change makes simple historical comparisons between pre-2020 and post-2020 M1 growth rates considerably less straightforward.
M2 remains useful because it captures a broader range of highly liquid monetary assets, but the important question is not whether M1 is growing faster than M2. The more useful analytical framework is to examine money growth, velocity, credit creation, nominal GDP, bank lending, household spending, and financial conditions together. The market does not care about one monetary aggregate in isolation. It responds to the interaction among them.
The Labour Market Is Another Transmission Channel
The original version also argued that employment data were substantially overstated, but the evidence needs to be stated precisely rather than politically. The Bureau of Labor Statistics’ 2025 benchmark revision ultimately reduced the seasonally adjusted March 2025 payroll employment level by 898,000, and the agency revised 2025 total nonfarm employment growth from 584,000 to 181,000.
That is a significant revision, but benchmark revisions are a normal part of the BLS process because survey estimates are periodically re-anchored to more comprehensive employment counts from unemployment-insurance records. The correct conclusion is therefore not that employment statistics were simply fabricated, but that investors should recognize the uncertainty inherent in real-time economic data and avoid treating preliminary numbers as immutable facts.
This matters for velocity because employment, income, consumption, and credit are connected. A stronger labour market can support spending and therefore velocity, while weakening employment can reduce household income, increase precautionary saving, and slow the circulation of money.
Bonds at the Crossroads
The relationship between velocity and bonds is useful but cannot be reduced to a mechanical rule that says velocity rises and bonds fall. Higher velocity can accompany stronger nominal demand and inflation pressure, which can push interest rates higher and bond prices lower, but bond markets also respond to growth expectations, fiscal deficits, central-bank policy, inflation expectations, term premiums, global capital flows, and risk sentiment.
The current environment demonstrates this complexity. U.S. Treasury yields have been rising alongside persistent inflation concerns, elevated oil prices, large fiscal deficits, and strong capital demand, including from AI infrastructure investment. Reuters reported that the 10-year Treasury yield was approaching 5% while the 30-year yield had reached levels not seen in many years, illustrating how multiple forces can converge on the long end of the curve. Velocity therefore belongs in the bond analysis, but it should not be mistaken for the bond analysis.
The Threshold Between Inflation and Disinflation
This is where the current cycle becomes particularly interesting. Velocity has recovered modestly, M2 has expanded again, and inflation remains materially above target, but the economy has not entered a runaway monetary spiral because the relationship between money, spending, production, and prices remains constrained by interest rates, credit conditions, productivity, fiscal policy, and supply capacity.
The critical signal would be a sustained acceleration in velocity occurring alongside expanding money and credit, resilient consumer demand, and persistent price pressure. That combination would suggest that disinflation is becoming considerably harder to achieve because monetary fuel is not merely accumulating, it is circulating faster through the economy. Conversely, if velocity stalls or falls while money growth remains positive, inflationary pressure could weaken even without an outright contraction in the money supply. That is the threshold worth watching.
The Psychology Behind Velocity
Velocity is ultimately a behavioural variable disguised as an economic statistic. People spend when they are confident, save when they are frightened, borrow when they believe the future will be better, and delay purchases when uncertainty becomes dominant, meaning the same monetary environment can produce dramatically different outcomes depending on the psychology of the participants.
This is where the idea of the human “machine” becomes useful without turning the economic analysis into mysticism. Gurdjieff’s broader concept of mechanical behaviour was that people often repeat patterns automatically without recognizing the forces driving them, and financial markets provide an almost perfect laboratory for that phenomenon because investors frequently respond to the same headlines, incentives, fears, and social cues without recognizing how predictable those reactions can become. The important question is therefore not whether people are machines. It is whether they can recognize when they are behaving mechanically.
Upstream Thinking: Watch the Flow
The mistake is to treat velocity as another economic number to memorize. The more useful approach is to watch the relationship between money supply, velocity, nominal GDP, inflation, credit, consumption, and financial conditions, because the interaction tells you whether monetary expansion is being absorbed, stored, or transmitted.
When money supply rises while velocity falls, the inflationary impulse may remain muted. When money supply rises and velocity rises, nominal demand can accelerate. When velocity rises while productive capacity is constrained, the inflationary consequences can become even more pronounced, because more money is chasing an economy that cannot expand supply quickly enough. This is where the concept becomes actionable. Do not simply watch how much money exists. Watch how quickly the system is using it.
Conclusion: The Money Matters, but the Motion Matters More
The velocity of money does not provide a magical inflation forecast, and it certainly does not operate independently of interest rates, labour markets, fiscal policy, commodities, credit, productivity, and supply constraints. What it does provide is a valuable window into the transmission of monetary conditions, showing whether money is sitting relatively dormant or circulating with increasing intensity through the economy.
The post-2008 experience demonstrated what happens when monetary expansion meets collapsing velocity. The post-COVID experience demonstrated what can happen when monetary and fiscal expansion meets a sudden acceleration in spending and constrained supply. The current environment is different again, because velocity has recovered modestly while M2 has expanded and inflation remains elevated, creating a monetary backdrop that deserves considerably more attention than the simplistic “inflation is cooling” narrative suggests.
The real signal is therefore not velocity alone. It is the change in velocity combined with the direction of money supply, credit, spending, prices, and economic capacity. Watch the flow and when the money starts moving faster, the entire machine can change.