
Buy When There’s Blood in the Streets: How Contrarian Investors Profit From Fear
Sept 03, 2026
Introduction: When Fear Creates Opportunity
Few investment phrases have survived as long as the idea that investors should buy when there is blood in the streets. The phrase captures a powerful principle of contrarian investing: periods of maximum pessimism can create opportunities that are almost impossible to recognize when fear dominates the financial landscape and the overwhelming majority of investors have become convinced that conditions will continue deteriorating indefinitely.
That does not mean every market collapse represents a buying opportunity, nor does it mean investors should recklessly purchase whatever happens to be falling the fastest. Contrarian investing is not blind optimism disguised as courage. It is the disciplined process of determining whether widespread fear has pushed the price of an asset significantly below its long-term value, while carefully distinguishing between temporary panic and genuine economic or corporate deterioration.
Markets regularly overshoot because human beings do. Greed can push prices far beyond reasonable valuations during periods of optimism, while fear can drive fundamentally strong businesses to prices that reflect catastrophe rather than reality. The contrarian investor attempts to recognize these emotional extremes without becoming emotionally trapped by them.
This requires patience, independent thinking, financial discipline, and a willingness to question the assumptions of the crowd. It also requires investors to understand one of the most powerful forces operating in financial markets: herd mentality.
Historical Context: When Market Panic Created Opportunity
Financial history repeatedly demonstrates that periods of extraordinary pessimism can eventually produce extraordinary opportunities, although history also makes it clear that buying during a crisis does not guarantee immediate success and that markets can remain depressed far longer than frightened investors, eager bargain hunters, or overconfident speculators expect.
During the Great Depression, the destruction of wealth and confidence was enormous, and the economic environment appeared hopeless to many participants who had watched the financial system collapse around them. Yet investors with sufficient capital, patience, and discipline were eventually able to acquire businesses and assets at prices that reflected extreme pessimism rather than their long-term capacity to generate value.
The 1929 stock market crash provides another important lesson because it demonstrates that recognizing a major decline is not the same as identifying the precise market bottom. Investors who purchased too early could still experience substantial additional losses before markets eventually recovered, which is why contrarian investing requires financial strength and appropriate position sizing rather than the assumption that the first major decline must represent the final opportunity.
The dot-com collapse demonstrated the other side of the equation. During the late 1990s, optimism surrounding technology became detached from financial reality as investors rewarded companies with extraordinary valuations despite weak profits, uncertain business models, and sometimes little more than a compelling narrative. When the bubble collapsed, countless speculative companies disappeared, but the collapse did not eliminate the long-term importance of the internet or technology itself. Investors capable of distinguishing durable businesses from speculative fantasies eventually found significant opportunities.
The 2008 Financial Crisis created another environment in which fear overwhelmed confidence as banks failed, credit markets seized, housing prices collapsed, and investors questioned whether the global financial system could stabilize. The recovery did not occur overnight, but investors who carefully accumulated financially resilient businesses during the crisis and its aftermath eventually benefited from one of the most powerful market recoveries in history.
The lesson is not that every decline should be bought aggressively. The lesson is that extreme pessimism deserves investigation rather than automatic surrender.
Mastering Market Dynamics: How Contrarians Think Differently
Contrarian investing begins with a simple observation: investors often become most confident when prices have already risen substantially and most fearful after prices have already fallen dramatically. This pattern does not mean the crowd is always wrong, because markets can continue rising during periods of optimism and falling during periods of legitimate economic deterioration, but emotional extremes can create situations where price and underlying value become disconnected.
The contrarian investor does not simply ask whether the crowd is optimistic or pessimistic. Instead, the more important question is whether the crowd’s emotional reaction has become disproportionate to the underlying reality.
A market can fall because investors are irrationally frightened, but it can also fall because the economic outlook has genuinely deteriorated. A company can become cheap because investors have panicked, but it can also become cheap because its business model is deteriorating, its debt burden is unsustainable, or its competitive advantage is disappearing. Contrarian investing requires the ability to tell the difference.
Harnessing Market Sentiment
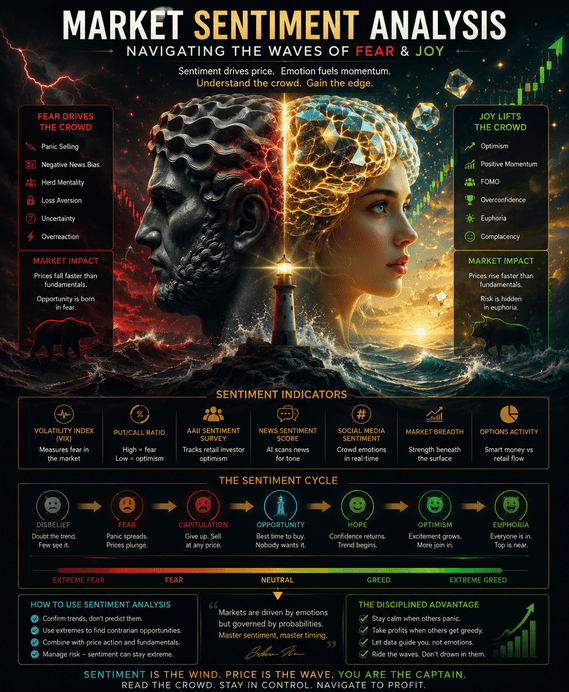
Market sentiment can provide valuable insight into the psychological condition of investors, particularly when optimism or fear reaches levels that historically suggest emotional extremes. Indicators such as the Volatility Index, put-to-call ratios, investor sentiment surveys, market breadth, and positioning data can help investors understand whether the market is experiencing unusual levels of fear or complacency.
However, sentiment should never be treated as an automatic trading signal. A high VIX does not guarantee that stocks are cheap, and a low VIX does not guarantee that a crash is imminent. Extreme fear can persist for long periods, particularly during major economic crises, while extreme optimism can continue long after rational investors believe valuations have become excessive.
The real value of sentiment analysis emerges when it is combined with valuation, fundamentals, technical conditions, and broader economic realities.
The critical question is not simply: “Are investors afraid?” The more useful question is: “Has fear pushed prices significantly below what the underlying assets are reasonably worth?” That is where disciplined contrarian analysis begins.
Identifying Contrarian Opportunities
Finding opportunities during periods of market distress requires more than watching prices fall. A declining stock can eventually become attractive, but price alone tells investors very little about the financial condition of the business beneath the chart.
Fundamental analysis helps investors examine whether a company possesses the financial strength necessary to survive difficult economic conditions and potentially emerge stronger after weaker competitors disappear.
Important considerations include:
- Balance-sheet strength
- Debt levels and refinancing requirements
- Cash flow generation
- Profitability
- Competitive advantages
- Management quality
- Industry conditions
- Long-term growth prospects
A company experiencing temporary market pressure may represent an opportunity. A company with overwhelming debt and a deteriorating business model may simply be heading toward deeper trouble.
Technical analysis can provide another layer of information by helping investors identify major support and resistance levels, momentum extremes, accumulation patterns, trend changes, and other signs that selling pressure may be exhausting itself. When combined with an understanding of market psychology, technical analysis can help investors determine whether a market decline appears increasingly disconnected from underlying fundamentals.
The strongest contrarian opportunities frequently emerge when fundamentals remain stronger than sentiment suggests.
Strategic Risk Management: The Difference Between Courage and Recklessness
Contrarian investing without risk management can quickly become expensive optimism. Markets can fall further than expected. Economic conditions can deteriorate more severely than analysts anticipate. Companies that appear cheap can become even cheaper, and businesses that once seemed financially secure can encounter problems that fundamentally change the investment thesis.
That is why position sizing matters. Even the strongest investment idea can be wrong, which means investors should avoid placing themselves in situations where one incorrect decision can permanently damage their portfolio. Diversification remains an important defense against concentration risk, particularly when uncertainty is high and future outcomes remain difficult to predict.
Investors should also distinguish between several very different situations:
- A temporary market decline
- A cyclical economic slowdown
- A structural deterioration in a business
- A heavily indebted company facing financial distress
- A fundamentally strong asset experiencing emotional selling
These situations can appear similar when viewed only through a declining chart, but their long-term outcomes may be dramatically different. The disciplined investor does not simply buy because prices are falling. They investigate why prices are falling.
The Psychology of Buying When Others Panic
The hardest part of contrarian investing is often not finding an opportunity. It is having the emotional discipline to act when every surrounding signal appears to suggest that acting would be dangerous.
When markets collapse, the psychological environment becomes increasingly hostile to rational decision-making. Headlines become more negative, forecasts become more catastrophic, and investors begin imagining scenarios that seemed impossible only months earlier. Every decline reinforces the belief that additional declines are inevitable.
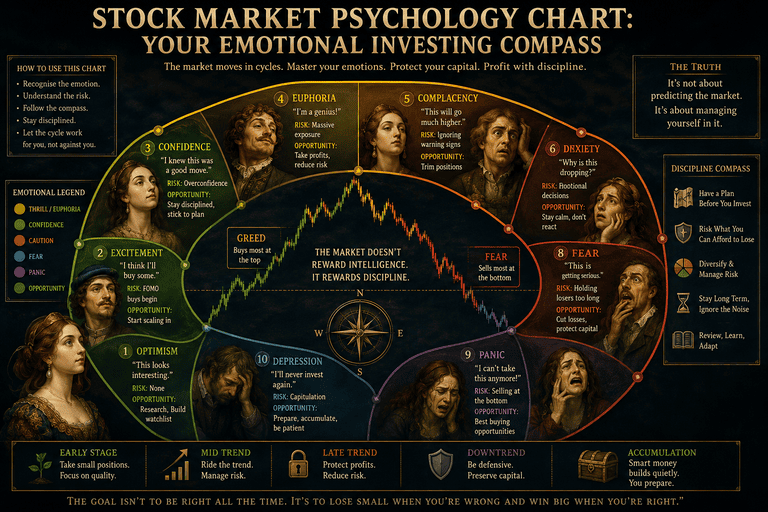
This creates a feedback loop. Falling prices generate fear. Fear generates selling. Selling produces further declines. Further declines convince more investors that the worst is yet to come. At some point, the market may move from rational concern into emotional capitulation. That transition can create opportunity, but only for investors capable of separating fear from analysis.
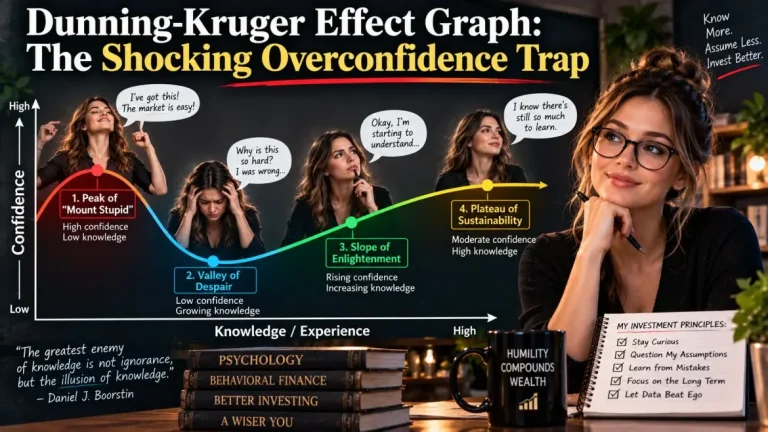
Emotional Control
Fear causes investors to abandon strategies that appeared perfectly reasonable before markets began falling. Greed causes investors to chase assets after optimism has already driven prices dramatically higher.
The disciplined investor attempts to treat market movements as information rather than instructions. A falling market does not automatically mean investors should sell and a rising market does not automatically mean investors should buy. Price movement must be interpreted within a larger framework of valuation, business quality, economic conditions, and risk.
Patience and Discipline
Contrarian investing frequently requires patience because markets do not immediately recognize value simply because an investor has identified it. A stock can remain undervalued for months. A market can remain pessimistic longer than investors expect. Economic conditions can deteriorate before they improve. This means the contrarian investor must be capable of tolerating uncertainty without constantly abandoning a well-researched strategy.
The objective is not to predict every short-term movement. The objective is to position intelligently when the potential long-term reward appears favourable relative to the risks involved.
Rational Decision-Making
Contrarian investing should never become contrarianism for its own sake. Buying an asset merely because everyone hates it is not automatically intelligent. Selling an asset merely because everyone loves it is not automatically intelligent either. The goal is independent thinking supported by evidence. Sometimes the crowd is wrong and sometimes the crowd is right. The disciplined investor investigates before deciding.
Long-Term Investing vs. Short-Term Trading
The philosophy behind buying when there is blood in the streets generally aligns more naturally with long-term investing than with short-term trading because the greatest opportunities created by major market dislocations often require substantial patience before the underlying value becomes visible again.
Long-term investors generally focus on business quality, valuation, competitive advantages, cash flow, and the ability of assets to compound over time. Major market declines can create opportunities to acquire strong businesses at prices that offer significantly better long-term return potential.
Short-term traders operate under a different framework. They may use volatility, momentum, technical levels, sentiment extremes, and market positioning to profit from shorter-term movements, but heightened volatility also increases risk and requires more active management.
Neither approach is inherently superior. The important issue is understanding which strategy you are using before entering the position. An investor should not purchase a stock intending to hold it for ten years and then abandon the strategy because the position declines over several weeks. Likewise, a trader should not enter a short-term position and suddenly transform into a long-term investor merely because the trade moves against them.
Examples of Contrarian Investing
Warren Buffett has repeatedly demonstrated the value of remaining rational when other investors become emotional. During periods of financial stress, Buffett has often examined opportunities created by fear and uncertainty, particularly when financially strong businesses or institutions could be acquired or financed on attractive terms.
His famous principle remains relevant: “Be fearful when others are greedy and greedy when others are fearful.”
The quote should not be interpreted as an invitation to buy recklessly during every market decline. Its deeper meaning concerns emotional extremes and the tendency of investors to make their worst decisions when greed or fear becomes overwhelming.
The aftermath of the dot-com collapse provides another example. The bursting of the bubble destroyed enormous amounts of speculative capital and eliminated many companies, but it did not eliminate the technological transformation already underway. Investors capable of separating failed speculation from durable businesses were eventually positioned to benefit from the continued growth of technology.
The Contrarian Investor’s Checklist
Before buying during a significant market decline, investors should ask difficult questions rather than assuming that a lower price automatically represents better value.
- Is the asset genuinely undervalued, or is it falling because the underlying business is deteriorating?
- Can the company survive prolonged economic weakness?
- Does the business have excessive debt or significant refinancing risk?
- Has sentiment become substantially more negative than the fundamentals justify?
- Am I buying because of analysis, or simply because the price has fallen dramatically?
- Can I financially and psychologically tolerate additional declines?
- What evidence would prove that my investment thesis is wrong?
- Am I properly diversified, or am I taking excessive risk because I am convinced that I have found the perfect opportunity?
These questions help prevent contrarian investing from becoming stubbornness disguised as conviction.
Conclusion: Fear Is Not the Enemy. Uncontrolled Fear Is
Market crashes are real. Recessions are real. Companies fail, bubbles burst, and investors can lose substantial amounts of money when speculation replaces discipline. Ignoring these realities is not contrarian thinking. It is denial, but history also demonstrates that financial markets repeatedly produce periods when fear becomes so intense that investors stop evaluating opportunities rationally and begin reacting emotionally to every negative headline, every price decline, and every prediction of further disaster.
During those moments, opportunity can quietly begin forming beneath the surface. The greatest investment advantage is not necessarily the ability to predict the next market crash, because consistently identifying precise market turning points remains extraordinarily difficult. The greater advantage may be the ability to remain rational when other investors become emotional.
The contrarian investor studies history, watches sentiment, examines fundamentals, and manages risk. They understand that market panic can create opportunity, but they also understand that opportunity without discipline can quickly become another form of speculation. When everyone is convinced that the future is hopeless, it may be worth investigating and when everyone is convinced that the future is limitless, it may be time to become cautious. That is the deeper meaning behind buying when there is blood in the streets.
The crowd reacts. The disciplined investor evaluates.
Over time, that difference between emotional reaction and disciplined analysis can matter far more than correctly predicting the next headline, the next market panic, or the precise day when fear finally reaches its peak.

Intriguing Articles