
The Wyckoff Strategy: Master Mass Psychology to See What the Crowd Misses
Sept 10, 2026
The Market Is a Mind Game, and Human Behaviour Leaves Footprints
Markets are often presented as machines driven by earnings, economic data, interest rates, and algorithms, but beneath all of those variables sits something far more persistent: human behaviour. Every rally, sell-off, breakout, and collapse represents millions of decisions being made under conditions of uncertainty, and those decisions are heavily influenced by fear, greed, expectations, social proof, and the desire to follow what appears to be working.
This is why the Wyckoff Strategy remains relevant. Richard Wyckoff’s framework was built around the interaction of supply and demand, but its deeper value lies in what those forces reveal about market psychology. Accumulation, markup, distribution, and markdown are not simply chart formations; they are recurring stages in the behaviour of investors as confidence moves from pessimism to optimism and eventually back toward fear.
Wyckoff does not provide a crystal ball. What it provides is a framework for asking a much better question: What are market participants actually doing, and what does their behaviour tell us about the next potential change in the market vector?
Wyckoff and the Psychology Behind Market Cycles
The market moves because investors act, and investors act because they form expectations about the future. When expectations become increasingly optimistic, demand expands and prices rise, while deteriorating expectations can produce the opposite effect as investors reduce exposure and supply overwhelms demand.
Wyckoff’s four broad phases provide a useful way to understand this psychological progression. Accumulation occurs when selling pressure begins to weaken and stronger demand gradually absorbs available supply. The crowd may remain pessimistic because the previous decline is still fresh in its memory, which is precisely why the market can stabilize without attracting widespread enthusiasm.
Markup begins when demand increasingly overwhelms supply and the market’s upward vector becomes visible. As prices rise, confidence returns, the narrative improves, and more participants enter because recent price behaviour provides psychological confirmation.
Distribution occurs when optimism becomes excessive and supply begins to absorb demand. Prices may continue rising, creating the appearance of strength, while momentum, breadth, or volume behaviour begins to reveal that the underlying force supporting the advance is changing.
Markdown develops when supply finally overwhelms demand. Fear replaces confidence, investors begin extrapolating recent losses into the future, and selling can accelerate as participants rush to exit positions that they were previously convinced would continue rising.
The importance of these phases is not that every market follows them perfectly. It is that they provide a behavioural map for understanding how expectations and capital flows evolve.
Mass Psychology: Why the Crowd Creates Extremes
Mass psychology explains why these cycles can become so extreme. Investors rarely evaluate markets in isolation because they constantly observe what other participants are doing, and this creates feedback loops in which rising prices increase confidence while falling prices increase fear.
Herd behaviour becomes particularly powerful when a narrative appears obvious. During euphoric periods, investors see rising prices as confirmation that they are correct, while negative information is dismissed as temporary noise. During panics, the same investors can reverse completely and interpret almost every piece of information as evidence that prices will fall further.
This is where confirmation bias becomes dangerous. Bulls search for evidence supporting higher prices, bears search for evidence supporting lower prices, and both can ignore information that contradicts their existing position. The Wyckoff approach encourages a different perspective. Instead of asking which narrative is correct, examine the relationship between price, volume, supply, demand, and behaviour. The market itself becomes the evidence.
Vector Psychology: Follow the Force, Not the Story
This is where Wyckoff becomes particularly powerful when combined with vector psychology. A market vector represents the dominant directional force created by the interaction of supply, demand, liquidity, sentiment, positioning, and expectations. Price tells you where the market has moved, but behaviour around that price helps reveal whether the underlying force is strengthening, weakening, or changing direction.
Suppose a market receives increasingly negative news but refuses to decline materially. That behaviour can be more informative than the headlines themselves because it suggests that available supply is being absorbed. Conversely, if extremely positive news produces only a marginal price response, the market may be signalling that demand is becoming exhausted.
The critical question is therefore not simply whether news is bullish or bearish. It is how the market responds to the news. When price behaviour contradicts the prevailing narrative, pay attention. Those divergences can reveal that the crowd’s interpretation and the market’s underlying vector are beginning to separate.
Accumulation: When Selling Stops Working
Accumulation is one of the most interesting phases because it often develops while sentiment remains poor. Investors who bought near the previous highs are frustrated, weaker holders continue selling, and the broader narrative may remain negative. Yet if the market repeatedly refuses to establish meaningful new lows, while selling pressure diminishes and demand absorbs available supply, something important is changing.
This does not mean that every sideways market represents accumulation. The investor must look for evidence that supply is actually being absorbed rather than assuming that consolidation automatically means a bottom. The psychological advantage comes from recognizing that the crowd often waits for confirmation. By the time everyone becomes confident that the market has recovered, much of the initial repricing may already have occurred.
Markup: When Psychology Turns Positive
Once demand gains control, the psychological environment begins to change. Higher prices generate confidence, confidence attracts additional buyers, and the improving price trend creates a new narrative. This is the stage where FOMO becomes powerful because investors who ignored the earlier opportunity begin to fear that they are being left behind.
This is also where discipline matters. A rising market can be fundamentally justified and still become increasingly vulnerable as expectations become excessive. The investor should therefore monitor whether the advancing vector remains healthy rather than assuming that every new high confirms the original thesis. A strong trend deserves respect. Excessive confidence deserves scrutiny.
Distribution: When Strength Begins to Weaken
Distribution can be difficult to recognize because the market may still appear exceptionally strong. Prices can remain near their highs while momentum weakens, volatility increases, breadth deteriorates, or large amounts of volume produce surprisingly little additional upside. These conditions do not guarantee an imminent decline, but they can indicate that supply is increasingly meeting demand.
This is where technical analysis becomes useful. Candlesticks, volume, RSI, moving averages, momentum, and breadth can help reveal whether the market is still advancing efficiently or whether the underlying force is becoming less effective. The mistake is to interpret every divergence as a sell signal. The better approach is to treat divergence as evidence that the existing vector deserves closer examination.
Markdown and the Psychology of Panic
When distribution gives way to markdown, the psychological environment can change rapidly. Investors who previously believed that every dip was a buying opportunity begin questioning their assumptions. Loss aversion intensifies, negative headlines multiply, and investors who bought near the top discover that their conviction was partly dependent upon continuously rising prices. Eventually, fear can become self-reinforcing. Selling produces lower prices, lower prices produce more fear, and fear creates additional selling.
Yet this is also where the greatest investment opportunities can begin to emerge. The investor should not automatically buy simply because prices have fallen. The objective is to identify when the selling has become excessive relative to the deterioration in the underlying asset and when evidence begins to suggest that the downward vector is losing strength.
The Contrarian Advantage: Behaviour Over Narrative
Contrarian investing is frequently misunderstood as simply doing the opposite of everyone else. That is not contrarianism; that is another form of emotional behaviour. A genuine contrarian studies what the crowd believes, determines how much of that belief is already embedded in price, and then watches for evidence that the underlying market behaviour is no longer confirming the dominant narrative.
When everyone is bullish but price momentum and breadth deteriorate, investigate. When everyone is bearish but selling pressure begins to exhaust itself and quality assets stop responding to negative news, investigate again. The goal is not to oppose the crowd. The goal is to understand the crowd well enough to recognize when its behaviour becomes extreme.
From Wyckoff to Investment Strategy
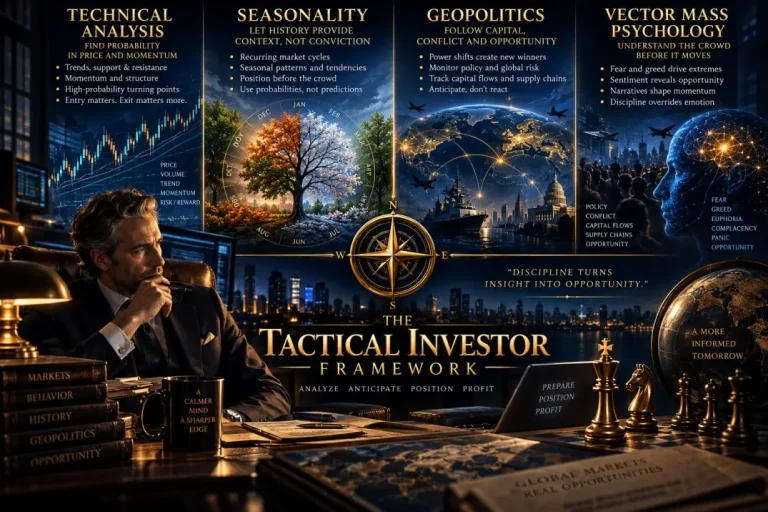
The greatest value of Wyckoff is that it can be translated from a trading framework into a broader investment philosophy. An investor can use Wyckoff principles to identify changing supply and demand, combine them with fundamental analysis to determine whether an asset is worth owning, and then use sentiment and technical behaviour to improve the timing of capital deployment.
This becomes particularly powerful during major market dislocations. When panic produces indiscriminate selling, the prepared investor can maintain liquidity and gradually deploy capital rather than attempting to predict the exact bottom.
For investors who already want to own a stock at a lower price, cash-secured puts can add another dimension to this process. Instead of simply waiting for a desired entry price, the investor can potentially collect premium while waiting and acquire the shares if the market reaches the chosen strike. That is the essence of getting paid to wait.
The Real Lesson of Wyckoff
Wyckoff is not about secret institutions controlling every tick of the market. It is about recognizing that large pools of capital leave behavioural footprints because meaningful accumulation and distribution affect supply, demand, volume, and price behaviour.
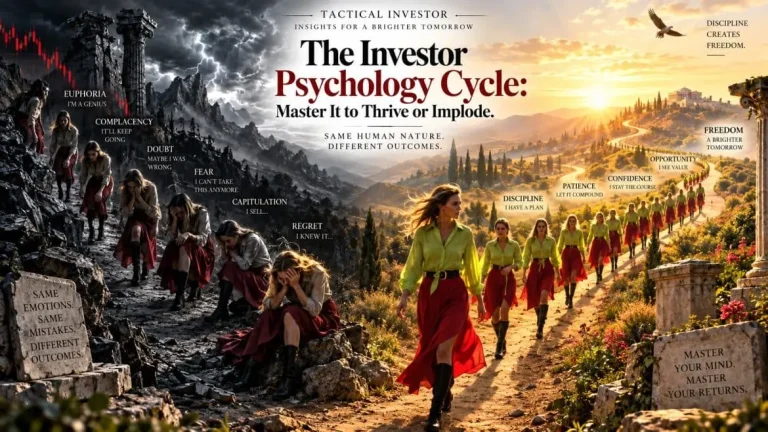
More importantly, those footprints exist within a larger psychological cycle. Investors become optimistic, then confident, then euphoric, and eventually complacent before fear reverses the process. The same human tendencies appear repeatedly because technology changes faster than human psychology.
That is why the combination of Wyckoff and mass psychology remains valuable. Wyckoff helps you study the market’s behaviour. Mass psychology helps you understand the people creating that behaviour. Vector psychology takes the analysis one step further by asking whether the dominant force is strengthening, weakening, or beginning to reverse.
The Market Is a Mirror
The market does not need to be manipulated for investors to make predictable psychological mistakes. Human beings create their own traps through herding, confirmation bias, recency, fear, greed, and the constant desire for certainty.
The investor who understands this stops treating every headline as a command to act. Instead, he watches how the crowd responds, how price reacts, where liquidity is moving, whether supply or demand is gaining control, and whether the prevailing narrative is being confirmed by actual market behaviour.
That is the real power of the Wyckoff Strategy. It is not a magic formula for predicting the next move. It is a framework for reading the relationship between price, capital, supply, demand, and human behaviour.
The crowd will continue chasing strength and fearing weakness because human nature has not changed. The prepared investor does something different: he watches the behaviour beneath the story, identifies the changing vector, preserves capital until the odds become attractive, and acts when the crowd’s emotional extremes create the greatest asymmetry. The market leaves footprints. Wyckoff helps you read them. Mass psychology explains why they exist. Vector psychology helps you understand where they may be leading.